

Ramp
Ramp Business Corporation
- 4.7
- 525.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
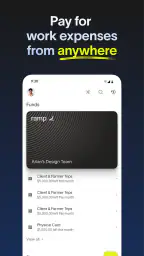
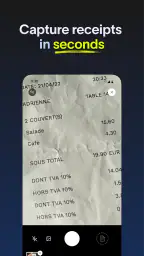
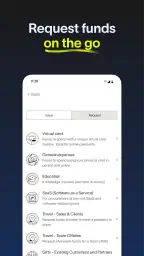
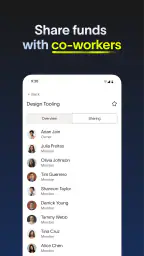
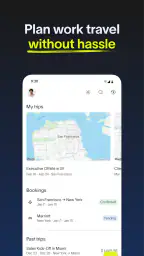
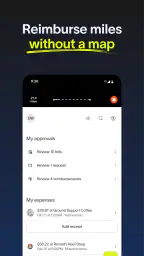
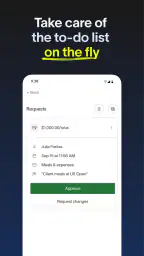
Ramp Pros and Cons
Pros
- Clean, intuitive interface that is easy to navigate
- Useful tools for organizing and managing digital assets
- Supports efficient workflows for teams and individual users
- Fast performance on most modern Android and iOS devices
- Helpful automation features can reduce repetitive tasks
Cons
- Some advanced features may require a paid subscription
- The initial setup can feel confusing for first-time users
- Performance may vary on older or less powerful devices
- Limited options for customizing certain areas of the app
- A stable internet connection is needed for many functions
 Analysis by All-app
I approached Ramp as a practical finance app rather than a flashy budgeting tool. Its purpose is easy to understand: help businesses keep an eye on spending and save time while handling everyday financial work. That focus makes it more interesting for a company or independent operator than for someone looking for a personal expense tracker.
What stood out to me first is how clearly the app sits in the business-finance space. Ramp Business Corporation develops it, and the app is free to install with an Everyone age rating. Its store summary, “Time is money. Save both,” is brief, but it points toward the main appeal: reducing the small administrative tasks that can quietly consume a working day.
I would not judge it like a banking replacement or a simple calculator. The useful question is whether it can become a convenient mobile companion for business spending. In my experience, that depends heavily on how much financial activity you manage, whether you work with other people, and how much you value having business information available away from a desk.
Where Ramp fits in everyday business finance
Ramp belongs to the finance category, but its audience is narrower than the category label suggests. A personal finance app is usually built around household budgets, bills, savings goals, or bank balances. Ramp is better understood as a business-oriented tool for people who need to stay close to company spending and related decisions.
That difference matters. A freelancer who only wants to record a few personal purchases may find a basic expense app faster and less distracting. A growing team, on the other hand, may benefit from a system designed around business activity rather than personal money habits. The app becomes more appealing when spending is shared, recurring, or connected to work that must eventually be reviewed.
The mobile format is especially useful for moments when I am not sitting at a computer. A purchase can happen during a client visit, while traveling, or between meetings. Being able to deal with a finance task in the moment is often more valuable than remembering to do it later, when receipts and context are easier to lose.
That is the central idea I took from using it: Ramp is most useful when it shortens the distance between a business transaction and the person responsible for understanding it. It is not necessarily about doing every financial job from a phone. It is about making the mobile part of the workflow less dependent on memory.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What the free price means in practice
The app is listed as free, so downloading it does not require an upfront purchase. That makes it straightforward to test whether its mobile approach fits your routine. It also means the initial decision is about time and suitability rather than paying before you can see whether the app feels useful.
Still, “free” should be interpreted carefully in a business-finance context. Free access to an app is not the same thing as a promise that every business service, account arrangement, or financial product connected with the wider platform will have no cost. I would treat the app’s listed price as the cost of getting the mobile application, then review any business terms separately before making a company-wide decision.
This distinction is important for owners who compare Ramp with accounting software, corporate card services, or expense-management platforms. Those alternatives can bundle software with other services, while a free app may be only one part of a larger business setup. I appreciate that the app can be tried without an upfront app charge, but I would not use that fact alone to calculate total operating cost.
For a small team, the sensible approach is to begin with a limited workflow. Use the app for a defined spending process, see whether it reduces follow-up work, and ask whether the people who need the information can actually use it comfortably. That test gives a more realistic picture of value than simply seeing the word free in an app store.
The experience I found most useful
Imagine a small consultancy where one person handles operations and several colleagues make purchases during the week. Without a mobile workflow, receipts can sit in email, messages, pockets, or a camera roll. By the time someone reconciles everything, it may be difficult to remember why a purchase was made or which project it belonged to.
In that situation, I would use Ramp as the point where the transaction becomes part of the company’s record while the details are still fresh. The practical benefit is not just speed. It is better context. A note made immediately after a purchase is usually more useful than a vague explanation added at the end of the month.
My advice is to establish a simple habit: deal with a business expense as soon as the transaction stops being obvious. If the purchase needs an explanation, add that explanation while the reason is clear. If a receipt needs attention, handle it before it becomes one of several nearly identical images. This is a small workflow change, but it is one of the more valuable ways a mobile finance app can save time.
A second useful scenario is remote approval or review. A manager may be away from the office when a spending question appears. A mobile app cannot replace a sensible company policy, but it can make the review less dependent on waiting for a laptop. That can be helpful when a delay would hold up a legitimate purchase or leave an employee unsure how to proceed.
Small habits that improve the result
The first habit I recommend is separating “capture now” from “review later.” Mobile devices are excellent for recording context at the right moment, but a small screen is not always the best place for a long cleanup session. Capture the information while traveling or between tasks, then reserve a calmer period for checking categories and exceptions.
The second is to agree on language inside the team. If one person describes a purchase by vendor, another by project, and another by purpose, later review becomes harder. A short, shared convention for notes can make the information much easier to scan. This is not a special button or hidden setting; it is a workflow advantage that comes from using the app consistently.
The third is to use mobile access for exceptions rather than constantly checking everything. Business owners often lose time by reviewing routine activity with the same intensity as unusual spending. I would focus attention on unfamiliar merchants, unusually timed purchases, missing context, or items that do not fit the expected business purpose. That approach makes the phone useful without turning it into a source of constant notifications and interruptions.
These habits also reveal a trade-off. Ramp can make financial work more immediate, but immediacy only helps when the team has clear responsibilities. If nobody knows who should review an item or when a task is complete, a faster capture process may simply create a larger pile of information.
How it compares with familiar alternatives
Compared with a basic personal budgeting app, Ramp feels better suited to company spending and shared responsibility. A personal budget tool is often quicker for tracking household purchases and monitoring individual categories. I would choose that kind of app for groceries, rent, savings, or personal subscriptions rather than bringing a business-focused workflow into private finances.
Compared with a spreadsheet, the main advantage is convenience at the point of activity. A spreadsheet can be flexible and inexpensive, especially for a very small operation. It can also be customized to match a company’s preferred columns and formulas. Its weakness is that it depends heavily on people remembering to open it, enter information correctly, and preserve supporting details. Ramp is more appealing when that manual discipline is becoming unreliable.
Compared with full accounting software, the choice is less straightforward. Accounting platforms usually cover a wider range of financial tasks and may be better for formal bookkeeping, reporting, tax preparation, or collaboration with an accountant. Ramp makes more sense as a mobile-facing part of a business spending process than as a reason to abandon every other financial system.
That is why I see it as complementary in many real businesses. A company may still need its established accounting process while using Ramp to make spending activity easier to manage during the day. The value comes from reducing friction before information reaches the more formal financial workflow.
Where the trade-offs become noticeable
The first limitation is audience fit. If you are managing only your own personal money, a business finance app may feel like too much structure for too little benefit. The more your needs resemble household budgeting, the more likely a dedicated personal finance alternative will be a better match.
The second limitation is that mobile convenience does not eliminate financial responsibility. An app can help a team capture and review activity, but it cannot decide whether a purchase was wise, whether a category is correct, or whether a company policy is clear. I would be cautious about presenting Ramp as an automatic solution to weak internal controls.
There is also a screen-size trade-off. Phones are excellent for quick action, checking a recent item, or handling a task away from the office. They are less comfortable for comparing long periods, inspecting many entries, or conducting a detailed financial review. Anyone expecting a complete desktop accounting experience on a phone may be disappointed by the format, even when the mobile workflow itself is convenient.
Another point is adoption. A finance app only creates shared value when the people involved use it in a reasonably consistent way. If one employee records every detail, another waits until the end of the month, and a third keeps separate notes, the company still has a coordination problem. Ramp may make good habits easier, but it cannot enforce genuine engagement by itself.
I would also avoid choosing it solely because its store rating looks strong. The app has a 4.7 average from around 2.3 thousand ratings, which suggests a generally positive reception, and it has passed 100 thousand installs. Those figures are encouraging, but they do not answer the most important question for an individual business: whether its workflow matches the way your team actually spends and reviews money.
Who is most likely to benefit
Ramp is a strong candidate for a small or growing business where spending happens across several people and the owner needs better visibility without waiting until the end of a reporting cycle. It is also worth considering for operators who travel frequently, work remotely, or regularly approve purchases away from a desk.
It may suit a company that has outgrown scattered receipts and informal messages but does not want mobile finance work to feel like a full bookkeeping session. The best users are likely to be people who value timely context: what was bought, why it was bought, and whether someone needs to review it.
The app can also be useful for an owner who wants to introduce more structure gradually. Instead of redesigning the entire finance operation at once, you can begin with one spending workflow and see whether employees follow it. If the process saves repeated questions and reduces end-of-week chasing, that is a meaningful result even before broader changes are made.
I would skip it, or at least postpone testing it, if your only need is a personal spending diary. I would also be cautious if your business already has a highly efficient process inside a desktop accounting platform and nobody needs mobile access. In that case, adding another tool could create duplication rather than savings.
It is probably not the right first choice for someone seeking investment guidance, detailed personal financial planning, or a general-purpose banking app. Its appeal is operational: managing business spending more conveniently. Choosing it for a different problem would make the experience feel unnecessarily complicated.
Device details and practical expectations
The current Android version is 0.159.0 and requires Android 11 or later. That requirement is reasonable for people using a relatively recent phone, but it matters if your company keeps older devices in circulation. Before asking a whole team to install it, check the phones they actually use rather than assuming every employee has the same operating system.
Because the app is aimed at business finance, I would also think about access habits before deployment. A shared company process should not depend on one person’s phone or one person’s memory. Decide who needs mobile access, which tasks belong on the phone, and when a more detailed review should happen elsewhere. That planning will do more for the rollout than simply distributing the app internally.
The Everyone rating makes the app broadly accessible from an age-classification perspective, but business suitability is still a separate matter. A young employee may be able to install it, yet the company should provide clear instructions about authorized spending, descriptions, and review responsibilities. Accessibility does not replace training.
My verdict on its value
I like Ramp most when I think of it as a practical bridge between spending and oversight. Its free app access lowers the barrier to trying that bridge, and the mobile format can be genuinely useful for businesses where receipts, approvals, and context otherwise arrive late. The strongest value is not a dramatic transformation; it is the accumulation of small moments when a task gets handled before it becomes a problem.
At the same time, I would not call it a universal finance solution. Personal users may be better served by a simpler budgeting app. Businesses with complex accounting needs may need a broader platform. Teams without clear spending rules may discover that the real issue is process design, not the lack of another application.
My recommendation is to try it if your company’s main frustration is the gap between making a purchase and properly recording or reviewing it. Start with one realistic workflow, establish shared habits, and judge the result by whether follow-up work becomes easier. If that gap does not exist in your business, there is little reason to add mobile finance software just because it is free.
Overall, Ramp earns my recommendation for business owners and teams who need faster, more organized spending visibility from a phone. I would keep expectations focused: use it to improve the operational side of company finance, not to replace every accounting or banking tool. In that role, it offers a sensible way to save time without pretending that good financial judgment can be automated.
Frequently Asked Questions
What is Ramp, and what can I use it for?
Ramp is a mobile application designed to help users manage their digital financial activity from one place. Depending on the version and region available, it may support services such as account management, card or payment features, cryptocurrency purchases, transfers, and transaction monitoring. The exact tools can vary by country, so it is important to review the app’s current description and supported services before registering.
Is Ramp available for both Android and iPhone?
Ramp is generally offered through official mobile app stores, including Google Play for Android devices and the App Store for iPhone, although availability may depend on your location. Before downloading, check the developer name, ratings, permissions, and recent update history to avoid unofficial copies. Your device must also meet the app’s operating-system requirements for installation and stable performance.
Do I need to verify my identity to use Ramp?
Identity verification may be required before accessing important Ramp features, particularly those involving financial transactions, payments, transfers, or cryptocurrency. The verification process can request personal information and an official identification document, and approval may not be immediate. Requirements differ according to local regulations and the services available in your country, so users should read the privacy and verification policies carefully.
Is Ramp safe to use for payments or financial transactions?
Ramp may include security measures such as account authentication, encrypted communication, transaction monitoring, and device or identity checks. However, no financial application is completely risk-free. Use the official download source, create a strong unique password, enable every available security option, and never share verification codes. Always confirm recipient details and review transactions regularly before approving payments or transfers.
Are there fees or restrictions when using Ramp?
Fees, limits, processing times, and supported payment methods can vary depending on your country, account status, transaction type, currency, and chosen funding method. Some charges may be displayed before confirmation, while network or third-party costs may apply separately. Before completing a transaction, carefully review the final amount, exchange rate, applicable fees, withdrawal limits, and any regional restrictions shown in the app.


